
How Is Tax Calculated on Annual Leave Payouts in Australia? (ATO Rules Explained)
When you leave a job, your annual leave balance converts to cash — and the ATO has specific rules for how that cash is taxed. The method is different from ordinary income tax, and the rate depends heavily on why you're leaving.
Annual leave paid out on termination is not taxed like a regular pay packet. The ATO applies a specific withholding method called Schedule 7 — separate from the standard Schedule 1 PAYG tables — and the effective rate depends on whether you resign, are made redundant, or leave under other circumstances. Getting this wrong is one of the most common payroll errors in Australia.
The key numbers
- Schedule 7 — the ATO's withholding method for unused leave paid when you leave a job
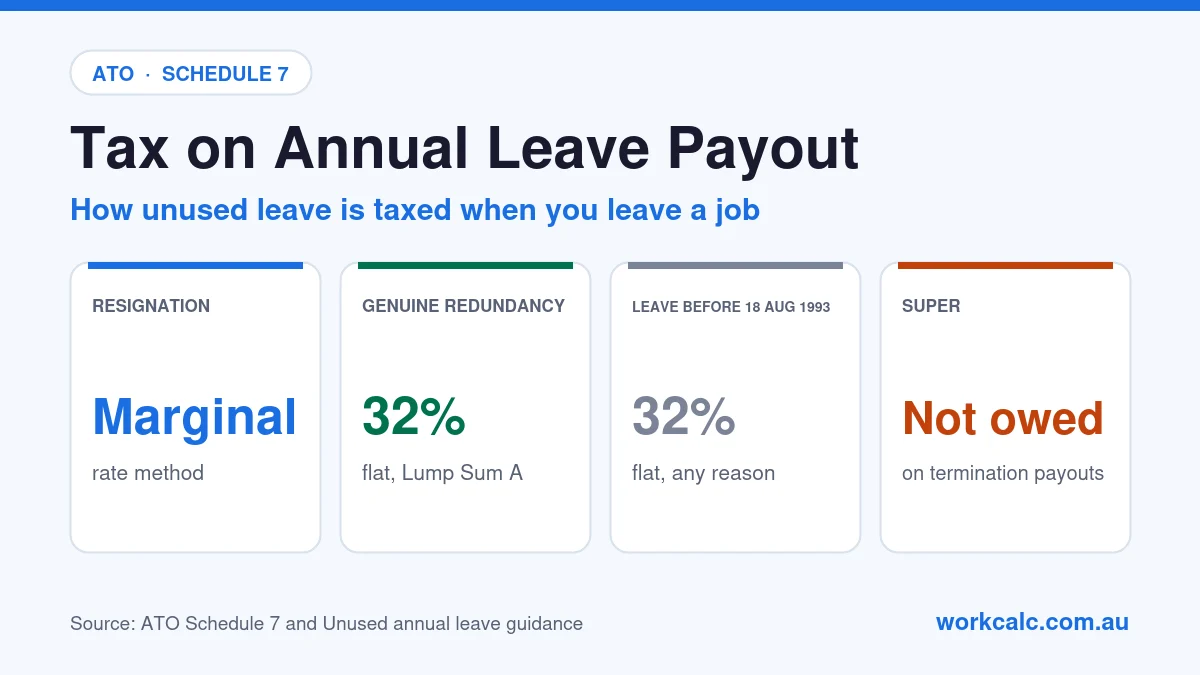
- Resignation or dismissal: marginal rate method, usually about 32% to 34% for incomes of $45,000 to $135,000
- Genuine redundancy, invalidity or early retirement: flat 32% on the whole payout, shown as Lump Sum A
- Leave accrued before 18 August 1993: flat 32%, whatever the reason you leave
- Leave loading is added to the payout and taxed the same way
- Super is NOT owed on unused annual leave paid on termination
- Tax is reconciled at year-end in your tax return — withholding is an estimate
Why annual leave payout tax is different from ordinary pay
When you receive ordinary wages each fortnight, your employer withholds PAYG tax using Schedule 1 — which annualises your pay and applies the corresponding marginal rate. If they did the same thing with your leave payout, the result would be punishingly high: the entire payout would be treated as if you earned that amount in every fortnight of the year.
Schedule 7 exists to prevent this. It spreads the payout across a year of pay periods, so the tax withheld is close to what you would pay if the payout had been earned evenly over the year.
The two methods — and which one applies to you
Schedule 7 has two methods. Which one applies depends on why your job ended, and it decides how much is withheld from your payout before you receive it.
Approved early retirement schemes are treated the same way as genuine redundancy. Leave accrued before 18 August 1993 is also taxed at a flat 32% and shown as Lump Sum A whatever the reason you leave, but few employees still have leave that old. Cashing out leave while you are still employed is different again: it is taxed as ordinary pay under Schedule 1.
How the marginal rate method works — step by step
For a resignation or dismissal, Schedule 7 uses these steps for leave accrued since 18 August 1993:
- Add up the payout. Unused leave hours × ordinary rate, plus leave loading if you get it. Confirm your balance with the Annual Leave Calculator.
- Work out the tax on one normal pay. Your employer uses the usual tax table for your pay cycle.
- Split the payout across a year. Divide it by the number of pay periods in a year (52 weekly, 26 fortnightly or 12 monthly), ignoring cents.
- Add that slice to one normal pay and work out the tax on the total.
- Take the difference. The tax from step 4 minus the tax from step 2.
- Multiply by the number of pay periods in a year. That is the amount withheld from your payout.
If the payout is less than $300, a flat 32% is withheld instead.
Worked example: resignation with 4 weeks of leave
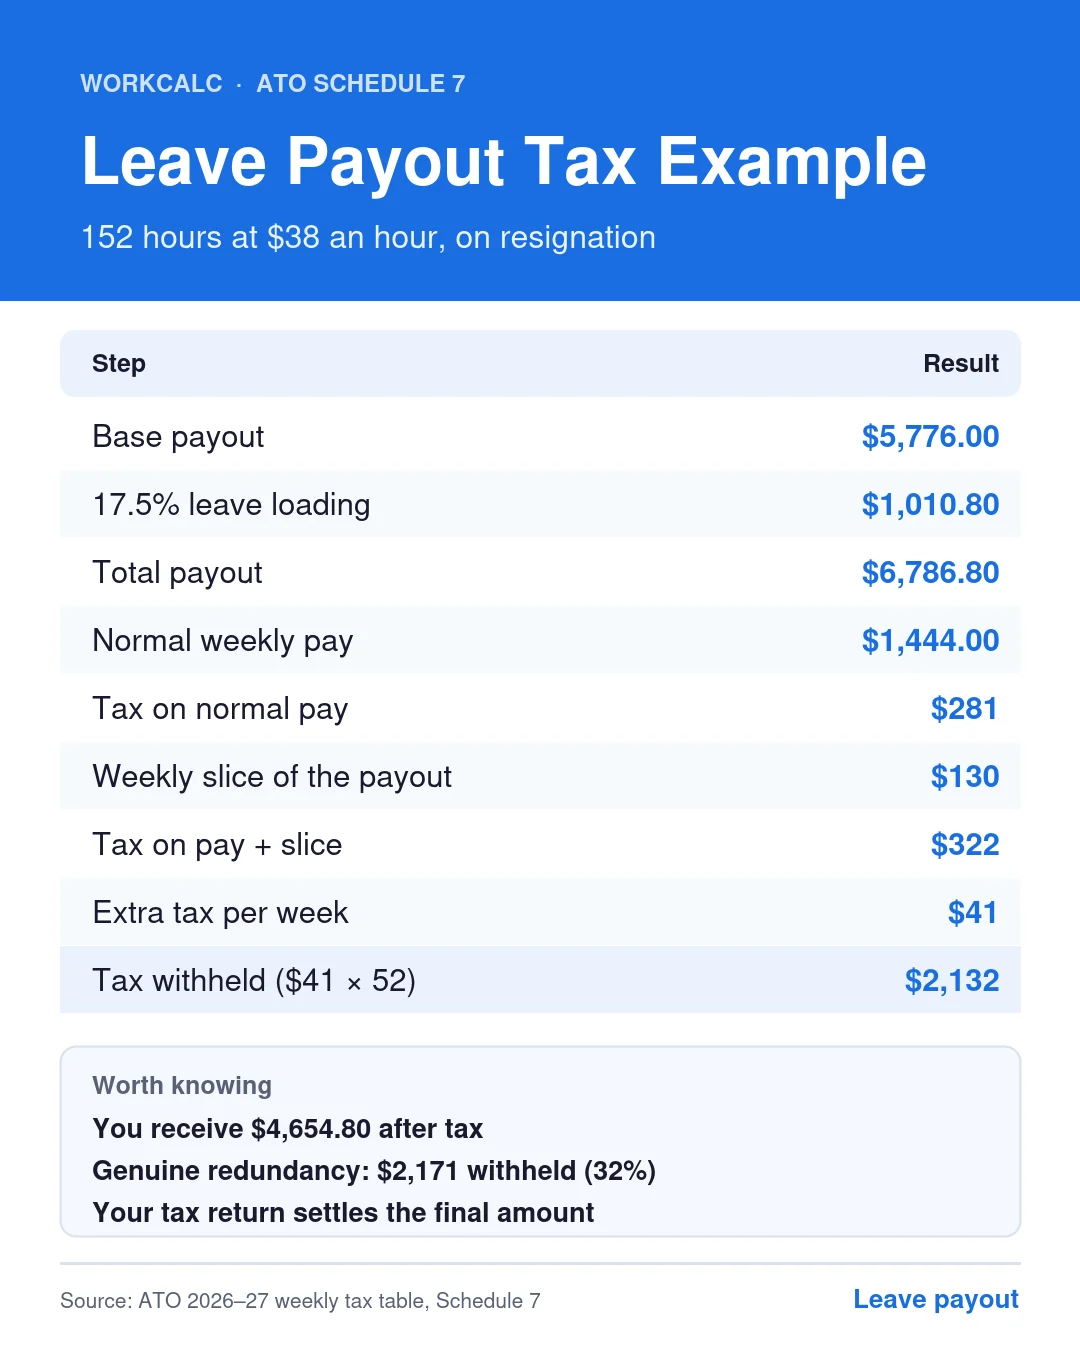
A full-time employee on $38 an hour, paid weekly, resigns with a full year's leave balance and gets 17.5% leave loading. They claim the tax-free threshold. Figures use the 2026–27 weekly tax table.
| Step | Calculation | Result |
|---|---|---|
| Base payout | 152 hrs × $38 | $5,776.00 |
| Leave loading (17.5%) | $5,776 × 0.175 | $1,010.80 |
| Total payout | $5,776 + $1,010.80 | $6,786.80 |
| Normal weekly pay | 38 hrs × $38 | $1,444.00 |
| Tax on normal pay | Weekly tax table | $281 |
| Weekly slice of the payout | $6,786.80 ÷ 52, cents ignored | $130 |
| Tax on normal pay + slice | Weekly tax table on $1,574 | $322 |
| Extra tax per week | $322 − $281 | $41 |
| Tax withheld from payout | $41 × 52 | $2,132 |
| Net payout | $6,786.80 − $2,132 | $4,654.80 |
About 31.4% of the payout is withheld, close to this employee's marginal rate of 30% plus the 2% Medicare levy. If the same payout were made because of a genuine redundancy, a flat 32% would be withheld: $2,171.
What appears on your income statement
How your payout appears on your income statement (formerly called a payment summary) depends on why you left:
- Resignation or dismissal: unused leave accrued since 18 August 1993, including any loading, is included in your gross payments with your other pay.
- Genuine redundancy, invalidity or early retirement: the payout is shown separately as Lump Sum A.
- Leave accrued before 18 August 1993: also shown as Lump Sum A.
Either way, the payout is part of your assessable income for the year. If your employer withheld too much tax, you receive a refund when you lodge. If they withheld too little, you pay the shortfall.
This means the withholding calculated at termination is always an estimate — your actual tax depends on your total income for the year, deductions, and personal circumstances that your employer cannot know.
Primary calculator Calculate your exact annual leave payout tax — all termination types, loading and LSL options →Is superannuation owed on annual leave payouts?
No. This surprises many employees. Under ATO rules, unused annual leave paid out on termination is excluded from Ordinary Time Earnings (OTE) — the base on which the Superannuation Guarantee (12% since 1 July 2025) is calculated. Your employer does not owe super on the leave payout component of your final pay.
This contrasts with annual leave taken during employment — when you're actually on leave, the leave pay is treated as ordinary earnings and super is payable on it at your employer's normal SG rate.
Does leave loading change the tax calculation?
No — leave loading that forms part of a termination payout is added to the unused leave amount and taxed under the same Schedule 7 rules. It doesn't get a separate tax treatment. The entire gross payout — base leave pay plus any loading — is treated as one figure for withholding purposes.
If you get leave loading when you take leave, it must be included in your payout too, even if your award or contract says otherwise. See Annual Leave Loading Explained: Who Gets 17.5%, Who Doesn't, and Why, or work it out with the Leave Loading Calculator.
Is the tax rate on redundancy leave payout lower than resignation?
It can be. In a genuine redundancy, a flat 32% is withheld from the whole unused leave payout. If you resign, the payout is taxed at about your marginal rate plus the Medicare levy.
For most people earning $45,000 to $135,000 the two come out about the same, because 30% plus the 2% Medicare levy is 32%. Above $135,000 the flat 32% is lower than your marginal rate. Below $45,000, marginal rates are usually lower than 32%.
The bigger difference between resignation and genuine redundancy is the redundancy payment itself — the tax-free amount and the ETP (Employment Termination Payment) rules. Those apply to the redundancy pay, not the annual leave payout. See Tax on Redundancy Pay Australia for the full breakdown, or the ATO's own unused leave payments guide →
When the payout spans two financial years
If your last day of employment falls near 30 June, your final pay — including the leave payout — may be processed in either the current or next financial year depending on when payroll actually runs. This matters because the payout is reported in the financial year it is paid, not the financial year your employment ended.
If you're near the end of a financial year, confirm with your payroll team which financial year the payout will be reported in. This affects which year's tax return you declare it on, and could affect your marginal rate depending on other income in each year.
Common mistakes employers make with leave payout tax
- Using Schedule 1 instead of Schedule 7. Ordinary PAYG tables annualise your regular pay rate and apply it to the payout — producing a much higher withholding amount than Schedule 7 requires. If your payout looks over-withheld, check whether your payroll used the correct schedule.
- Leaving loading out of the payout. If you get leave loading when you take leave, it must be included in your unused leave payout and taxed with it.
- Using the flat 32% rate for a resignation. The flat 32% only applies to genuine redundancy, invalidity, early retirement or leave accrued before 18 August 1993. On a resignation it can under-withhold for higher earners.
- Paying super on the payout. Super is not required on unused annual leave paid on termination — including any loading component.
Disclaimer: This article reflects current ATO Schedule 7 withholding rules. Tax treatment of termination payments depends on individual circumstances — the ATO's published guidance and tax tables are authoritative. For advice specific to your situation, consult a registered tax agent. WorkCalc Australia is independent and not affiliated with the ATO or Fair Work.
Frequently asked questions: tax on annual leave payouts
Plain-English answers on Schedule 7, Lump Sum A, redundancy rates, super and how the ATO marginal rate method works.
How is tax calculated on an annual leave payout in Australia?
Your employer withholds tax from an unused annual leave payout using ATO Schedule 7. If you resign or are dismissed, the payout (including any leave loading) is split across a year of pay periods, one slice is added to a normal pay, and the extra tax on that slice is withheld for every pay period in the year. The result is close to your marginal rate. For a genuine redundancy, invalidity or early retirement, a flat 32% is withheld instead. Your final tax is worked out when you lodge your tax return.
What is the tax rate on annual leave payout for resignation?
There is no fixed rate. If you resign, tax is withheld at about your marginal rate plus the 2% Medicare levy, using the ATO's Schedule 7 marginal rate method. For most people earning $45,000 to $135,000 that is about 32% to 34% of the payout.
What is the tax rate on annual leave payout for redundancy?
For a genuine redundancy, a flat 32% (including the Medicare levy) is withheld from the whole unused leave payout, including loading, and the payout is shown as Lump Sum A on your income statement. The same applies to invalidity and approved early retirement schemes.
What is Lump Sum A on a tax return?
Lump Sum A is an ATO label on your income statement for some unused leave paid when you leave a job: leave paid because of genuine redundancy, invalidity or an approved early retirement scheme, and leave accrued before 18 August 1993. If you resign or are dismissed, unused leave accrued since 18 August 1993 is not Lump Sum A; it is included in your gross payments.
Is super paid on annual leave payouts?
No. Unused annual leave paid on termination is excluded from Ordinary Time Earnings under ATO rules, so the Superannuation Guarantee (currently 12%) does not apply. Note: super IS owed on leave actually taken during employment — that's treated as ordinary earnings. Only the termination payout is excluded.
What is the difference between Schedule 7 and ordinary PAYG withholding?
Schedule 1 is used for your normal pay. If your employer used it on a leave payout, the whole payout would be treated as one pay period's income and taxed at a much higher rate. Schedule 7 spreads the payout across a year of pay periods instead, so the tax withheld is close to your marginal rate.
Is leave loading taxed the same way as the leave payout?
Yes. Leave loading paid out when you leave is added to your unused leave and taxed the same way under Schedule 7. There is no separate treatment for the loading.
What if my employer withheld too much or too little tax?
The withholding is reconciled at year-end when you lodge your tax return. If your employer over-withheld, you receive a refund. If they under-withheld, you pay the shortfall. The ATO's assessment is based on your total assessable income for the year — the employer's withholding is an estimate, not the final determination of tax owed.